What Bali Property Returns Are Actually Achievable
"What return can I realistically expect from a villa in Bali?"
This is the question we hear most often from investors, and for good reason. Every developer in Bali has a slide with double-digit return projections on it, yet almost no one publishes actual results. Whether you're buying off-plan or a finished villa, there's one thing we always emphasise from the outset: rental yield alone rarely gets you to double digits. A genuinely strong return comes from a realistic yield, a sensible entry price, and appreciation.
Here's what is actually achievable, using our own numbers from ADAYA rather than someone else's.
Key Takeaways
- Stabilized net yield: A stabilized, well-located, professionally managed Bali villa delivers a net rental yield of roughly 8–9% a year and can cross 10% in good sub-markets and a strong project brand.
- Yield plus appreciation: Yield alone rarely gets you to double digits. Yield plus appreciation does, and on our own asset the combination produced a 35.3% total return on cost over thirty months, a 12.8% compound annual growth rate.
- A genuinely competitive market: Bali remains a highly attractive investment option, offering double-digit total returns and 2-3x the net yields of markets like Dubai, Singapore, Hong Kong or Australia.
The Evidence Base
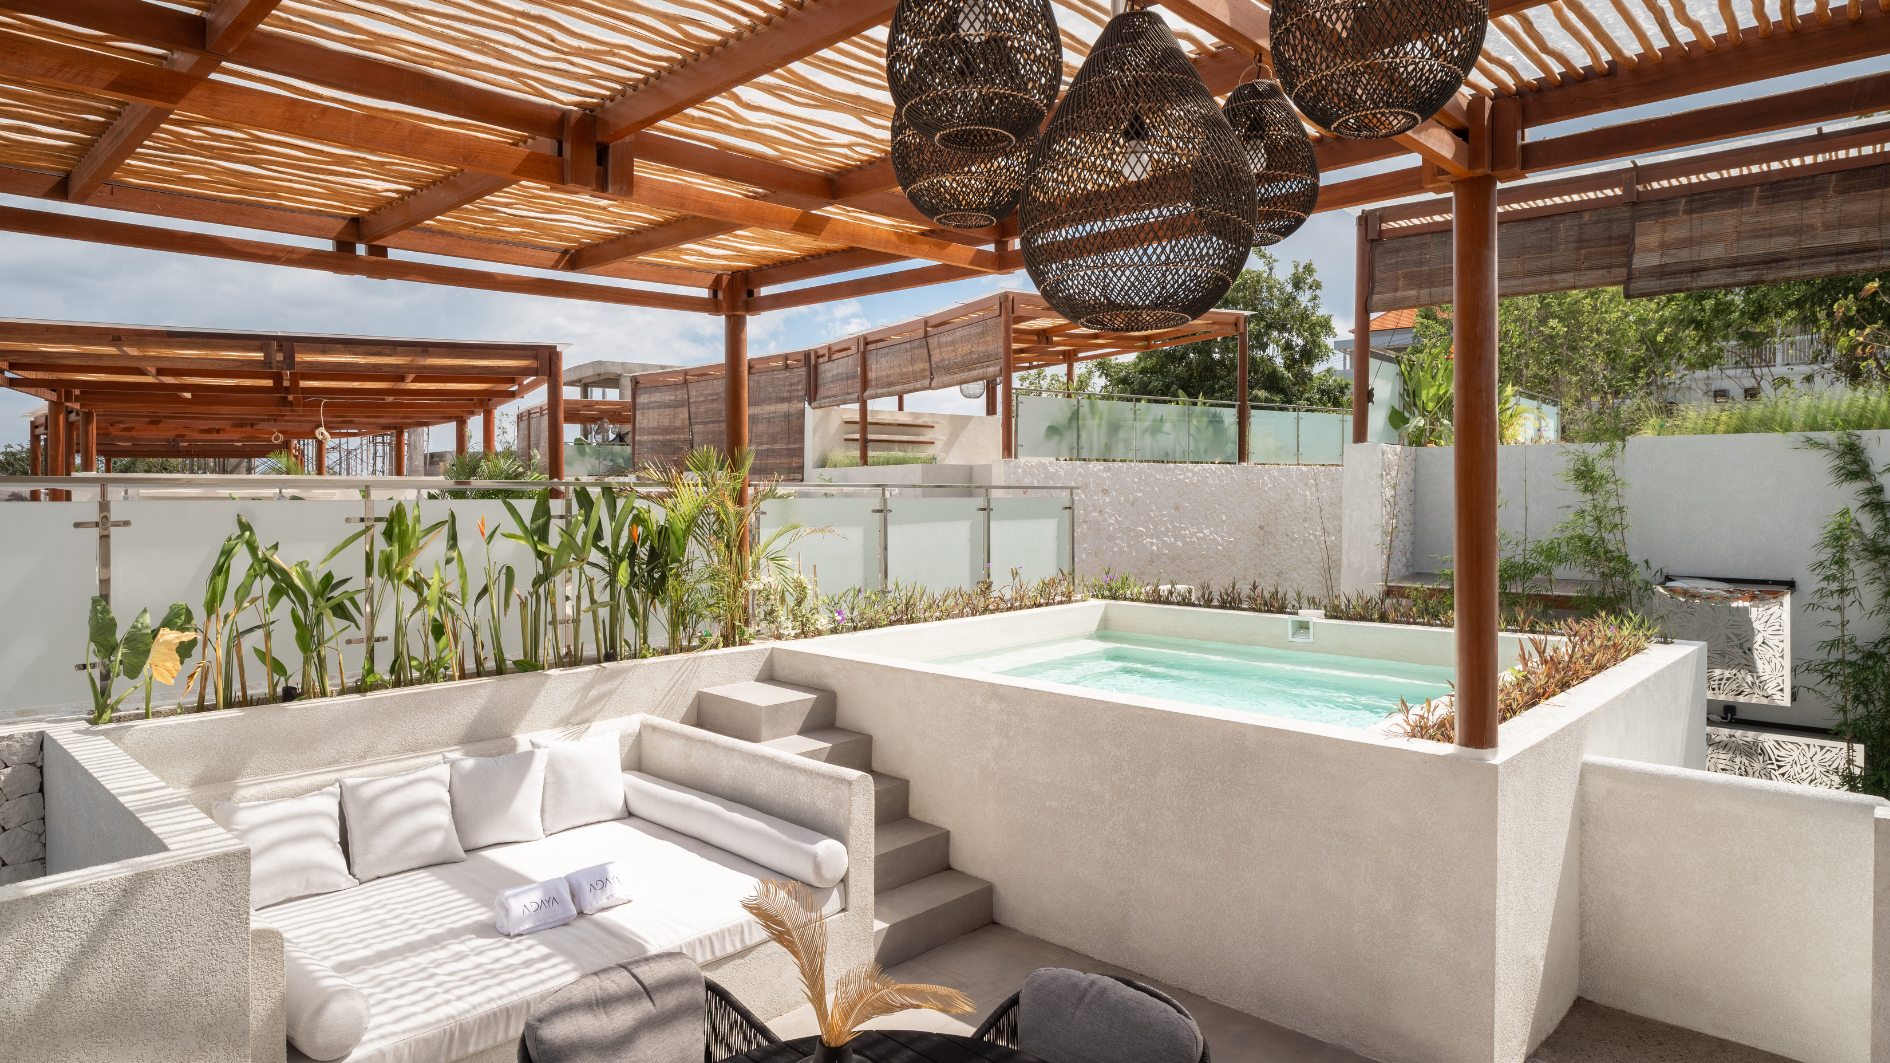
We run operations at LeyLines. We built ADAYA, twelve one-bedroom villas on the ridge above Dreamland on Bali's Bukit peninsula, and we now manage them ourselves. Early investors bought at US$200,000 in Q1 2024. Income started in May 2025.
We have fifteen consecutive months of operating data to 31 July 2026, six months of which have been independently verified by Bali-based accounting firm PT Trident Treehouse. That is the entire evidence base for what follows. Where the data is unaudited, we say so.
What the Independent Verification Says
Trident Treehouse reviewed June to November 2025 across the twelve-unit complex. Against a total investment basis of US$2,447,993 they verified:
| Line | Amount |
|---|---|
| Total revenue | US$201,590 |
| Imputed revenue, owner stays | US$26,764 |
| Total expenses | US$68,397 |
| Net profit before tax | US$159,957 |
That produces two return figures, and the difference between them matters.
Excluding owner stays: 5.65% over six months. This is cash performance only, the realised rental income actually collected.
Including owner stays: 6.53% over six months. Owners occupied their own villas during the period. Those nights generate no cash but they do consume inventory that would otherwise have sold. Trident valued each owner-stay night at the prevailing average daily rate for that month and treated it as imputed revenue, adding US$26,764. Because there is no corresponding operating cost, the entire amount drops to net profit and lifts the return by 0.88 percentage points.
We think including owner stays is the right treatment for an owner-occupier and the wrong one for a pure investor. If you intend to use the villa, the economic benefit is real and 6.53% is your number. If you intend to rent it out year-round and never set foot in it, 5.65% is what your bank account would have seen. Most projections you will be shown do not tell you which of the two they are quoting.
Annualized by doubling, those become 11.30% and 13.06%. A very strong operational start in a high-demand market.
The Full Fifteen Months
Here is the whole period, per unit, on the US$200,000 acquisition basis. Net yields are annualized monthly figures.
| Period | Net yield p.a. |
|---|---|
| Jun–Nov 2025, independently verified, excl. owner stays | 11.30% |
| Jun–Nov 2025, independently verified, incl. owner stays | 13.06% |
| Average, 14 operating months ex-handover | 8.72% |
| Average, all 15 months incl. handover | 8.23% |
8.72% across fourteen operating months is the figure we would underwrite. It covers a full high season and a full low season, and it is roughly half of what the loudest projections in this market promise.
Bali Seasonality Is Not a Footnote
Monthly net yields across the period ranged from 15.75% in August 2025 to 3.03% in December 2025. A factor of five between the best month and the worst, in the same building, with the same management and the same cost base.
November through March sat below 5% in every month. July and August cleared 14%. The practical consequence: if you are relying on this income to service a loan or fund living costs, model the low season, not the average. An owner drawing a flat monthly distribution off an 8% annual number will be underwater from November to March and made whole in July. That is a cash-flow design problem. It is solvable, but only if you know it is coming.
One further honesty note. February 2026 shows 1.31% because we transferred management that month and the rental pool temporarily dropped from eleven units to seven, rebuilding to eleven by May. We exclude it from our headline average and flag it every time. That month is a fair illustration of what an operational disruption costs: roughly a full percentage point off the fifteen-month average.
Where Double-Digit Bali Returns Actually Come From
An 8.72% net yield is not a double-digit return. Anyone selling you one on rental income alone is quoting gross, or a peak window, or a projection. The double digit is real, but it comes from two engines rather than one, and it is worth being precise about which is which.
Engine One: The Development-Phase Pricing Gap
This is the one we can evidence directly. ADAYA early investors bought at US$200,000 in Q1 2024. The final unit of the same type transacted at US$250,000 in late 2024. That is 25%, achieved in the pre-completion window, and it is an achieved transaction price rather than a list price, a broker opinion or a valuation.
It is also a one-time event, not an annual rate. Early buyers are paid for taking construction risk and holding through a period with no income. Once the building is finished the gap is closed and it does not repeat.
Here is the full decomposition on that unit:
| Component | Amount | % of cost |
|---|---|---|
| Net rental income, 15 operating months | $20,572 | 10.3% |
| Unrealised capital appreciation | $50,000 | 25.0% |
| Total value and income | $70,572 | 35.3% |
| Annualised over 30 months, simple | — | 14.1% p.a. |
| Compound annual growth rate | — | 12.8% p.a. |
That is a genuine double-digit outcome, and note where it came from: appreciation contributed roughly seven-tenths of it. The capital position is deliberately frozen at late 2024, so nothing the Bukit has done in the twenty months since is reflected. Neither figure is an internal rate of return.
Engine Two: Market Appreciation After Completion
This is where we would be careful, because almost every published Bali appreciation figure comes from someone selling Bali property, including this one. Read them accordingly.
The bullish end of the market data has island-wide land values up roughly 15–30% over the past two years, with Uluwatu and the Bukit repeatedly named as the fastest-appreciating corridor on the back of infrastructure work, a shrinking supply of premium coastline and tighter zoning. Some agencies put Uluwatu's annual appreciation at 15–20% since 2021.
The conservative end of the same market data is more useful. Median sold prices stabilised around US$299,000 in late 2025 after an earlier 5% correction, prime corridors including Uluwatu are forecast at 3–7% appreciation for 2026, and oversupplied generic product is expected to stay flat.
We would underwrite the conservative end. Low-to-mid single digits, on quality product in a corridor with a supply constraint. Anything above that is upside you did not pay for.
What That Combination Produces
Take the verified 8.72% net yield and add market appreciation on top. This is simple addition against original cost rather than an IRR, and it assumes the yield holds.
| Annual market appreciation | Total annual return |
|---|---|
| 0% | 8.7% |
| 3% | 11.7% |
| 5% | 13.7% |
| 7% | 15.7% |
You need roughly 1.3 points of appreciation to cross into double digits. That is the honest version of the double-digit claim, and it is a low bar in a market forecast at 3–7% on prime product.
Two buyers, two different products:
- Off-plan: You accept 12–18 months with no income and construction risk. You are paid the development-phase gap, 25% on ADAYA, plus market movement thereafter. This is where the low-teens CAGR lives.
- Finished and stabilised: You start earning in month one at roughly 8–9% net and take market appreciation only. Cleaner, lower, and it starts immediately.
Both are legitimate. The market conflates them constantly, and that conflation is where the 15–20% brochure numbers come from: a development-phase gap presented as if it were an annual rate.
Currency Risk in USD Terms
Everything above is in US dollars. The rupiah moved from 16,314 to 18,078 to the dollar across the period, weakening about 11%.
Had the currency held at its May 2025 level, the same rupiah earnings would have converted to roughly US$230,000 rather than US$221,667: about US$8,500, or 3.8% of net income, given back to FX. The operating business performed slightly better than the dollar numbers suggest. If you earn or spend in rupiah your return is higher than what we have shown. If you are underwriting in dollars, your return will depend to some extent on FX rates, but not as much as most expect: 3.8% of net income is a mild swing, and a lower IDR also reduces operational expenses.
Bali Rental Yields vs Dubai, Singapore, London and Sydney
We get asked constantly whether Bali is worth the complexity relative to a mature market. Here is the fair comparison of typical net rental yields:
| Market | Typical net rental yield |
|---|---|
| Singapore | 2–3% |
| Hong Kong | 1–2% |
| London | 2–3% |
| Sydney | 2–3% |
| Dubai | 4–5% |
| Bali, ADAYA verified | 8.72% |
Those gateway-city figures compress further once you are a foreign buyer. A non-resident landlord in the UK pays income tax on rental earnings at up to 45% and stamp duty of up to 17% on a purchase, before service charges and ground rent. Run the arithmetic: a £400,000 London property yielding £18,000 leaves a 40% taxpayer with about £10,800, roughly 2.7% before any maintenance or management.
The genuine competitor is Dubai. Gross yields there averaged 6.68% as of April 2026, and net yields typically land between 4% and 5%. Dubai also offers a dollar-pegged currency, no personal income tax on rental income, freehold title and far deeper liquidity.
So ADAYA's 8.72% sits at roughly two times stabilized Dubai and roughly three times a net London or Singapore yield. That premium is real, and it is payment for a seasonal hospitality market that is still maturing.
What Bali Property Returns Are Actually Achievable
For a well-located, professionally managed Bali unit bought at a sensible price, here is what we would underwrite:
- 8–9% net per year with potential to 10%+ once fully stabilized and established, subject to FX rates.
- A five-fold swing between peak and trough months. Budget cash flow monthly, not annually.
- Capital appreciation as compensation for the pre-income period, being the real driver of double-digit returns.
That gets you to something in the low teens as a total annual return if the appreciation shows up, and a high single digit if it does not. That is a good investment. It does not need to be dressed up.
Our Outlook: Clearing 10% on Yield Alone
Everything above is what has already happened. Here is what we are managing toward, stated as a target rather than a projection.
We are aiming to clear 10% annualised on rental yield alone, before any appreciation. We think that is reachable in years two to three of a building's operating life, which for ADAYA means 2026/2027.
The gap is 1.3 points. On a US$200,000 unit that is about US$2,600 a year, which at our current 49% flow-through means roughly 16% more revenue per unit against the same cost base. It comes from three places.
The low season is the biggest single lever, and we are attacking it with groups. November through March ran between 3.0% and 4.8%. High season is already close to capacity, so there is little left to win there. Lifting the four weakest months by three points each would add roughly 1.0 points to the annual average on its own, over half the gap, from the part of the year most operators write off.
The conventional answer to a soft February is to discount, which fills rooms and lowers ADR at the same time and leaves you no better off. Our answer is to bring demand that does not come from the booking platforms at all.
We are launching LeyLines Tours, starting with five-night wellness retreats built around the villas and a nearby sports and recovery club, sold to fitness and wellness coaches in Hong Kong and Singapore. The coach brings their own community and runs the programme; we handle accommodation, transfers, training facilities, food, therapists and excursions. Bali is five hours direct from Hong Kong and under five from Singapore, which makes a long weekend plus two days a realistic proposition for people who cannot take a fortnight off.
Three things make this the right instrument for the trough specifically:
- Counter-seasonal by design: Our first departure is targeted for November or early December 2026, deliberately the two weakest months, rather than the two strongest.
- It books whole buildings, not rooms: A group of ten takes ten private villas for five nights, roughly 15% of a month's entire inventory in a single booking, at rate rather than at a distressed discount.
- It is direct and it is not price-led: The guest comes from the coach's audience, so there is no platform commission inside the cost line and no need to undercut the market to win them.
We've done similar trips for families, catered to their needs and they loved it. It is the specific mechanism behind the low-season claim, and it is why we think the shape of the year changes before the peak does.
Direct bookings: Every booking that comes to us rather than through an OTA converts a cost into margin without raising the guest's rate. With over 5,000 followers on Instagram, we now receive 22% of our bookings through direct channels, a solid base we're growing every month.
Ranking and rate: A listing with a long review history at 4.84 prices above a new one with twenty reviews. That is earned over seasons, not bought.
All three are the same job: brand. This is the honest reason we think year two to three rather than year one. A villa that is a commodity on a booking platform takes whatever the market gives it in February. A villa that is part of a place people have heard of, want to return to, and recommend, holds rate in the shoulder season and fills from its own channel. That is why we brought management in-house, why we are building amenity and F&B into the new Balangan projects rather than selling isolated villas, and why the guest rating matters commercially and not just as a nice line in a brochure.
So: buy on 8.72%. If we do our job, 10% on yield alone is where this gets to, and with appreciation on top that is a 13-18% total return.
Three Questions Worth Asking Any Bali Developer
- Show me the waterfall from gross room revenue to my bank account, with every deduction named and quantified.
- Show me twelve consecutive months rather than a selected window and tell me which months are independently verified.
- Show me the worst month, tell me what happened in it and how you will deal with it next year.
We publish all three for ADAYA, including the February we would rather not talk about. If a developer will not, that is your answer.
Request the ADAYA Track Record
Everything in this article is summarised from one document. The ADAYA 1BR Track Record, May 2025 to July 2026. Fifteen consecutive months, per unit, in US dollars:
- Month-by-month gross revenue, tax and service charge, management and marketing fees, operating expenses, net income and net yield
- The exchange rate applied in each month
- The full gross-to-net waterfall and the capital position
- Every independently verified month marked as such, and thirteen notes setting out the basis of preparation, including the months we exclude and why
Frequently Asked Questions
What is a realistic rental yield for a Bali villa in 2026?
Roughly 8–9% net per year for a stabilised, well-located, professionally managed property. Our own verified data shows 8.72% across fourteen operating months. Figures of 15–20% are typically gross, or taken from a peak-season window.
What is the difference between gross and net rental yield in Bali?
Gross yield measures room revenue against purchase price. Net yield is what remains after management fees, hospitality tax, service charge and operating expenses.
How seasonal is Bali rental income?
Highly. Our monthly net yields ranged from 15.75% in August to 3.03% in December, with November through March below 5% in every month.
Can you get a double-digit return from Bali property?
Yes, you can reach 13-17% total return considering both rental income and appreciation. Buying off-plan adds the development-phase pricing gap on top.
Will Bali yields improve over time?
They can. A new building runs below its stabilized potential while it builds review history, direct booking share and shoulder-season rate. We are targeting 10% on yield alone in years two to three, which on our numbers requires about 16% more revenue per unit against the same cost base. It is a target with specific measures in place, not a projection.
How do Bali yields compare to Dubai?
Bali runs at roughly double the net yields of Dubai.
Author: Sebastian Link, Co-Founder & COO, LeyLines Group — a vertically integrated developer and hospitality operator on Bali's Bukit peninsula.
Interested in learning more about investment opportunities in Bali?
EXPLORE OPPORTUNITIES